Anyone searching for “Universal Credit cost of living payment when will it be paid” is likely hoping for another government payment to help manage increasing household expenses.
However, the Department for Work and Pensions (DWP) has confirmed that there will be no new nationwide Cost of Living Payment in 2026, and no further payments are currently planned.
The last means-tested Cost of Living Payment was £299, which most eligible Universal Credit claimants received between 6 February and 22 February 2024.
This does not mean financial assistance has disappeared. Universal Credit continues to be paid, benefit rates increased in April 2026, and additional assistance is available through local councils, housing support and energy-bill schemes.
We analysed the current benefit rules, previous payment schedules and the government’s replacement support arrangements to explain exactly what claimants can expect in 2026.
Is There a Universal Credit Cost of Living Payment in 2026?
No. There is no confirmed Universal Credit Cost of Living Payment for 2026.
The government has explicitly stated that the previous national Cost of Living Payment programme will not continue in 2026.
That means individuals receiving Universal Credit should not expect another automatic £301, £300 or £299 payment under the previous scheme.
| Common question | Confirmed position in 2026 |
| Will DWP pay another Cost of Living Payment? | No new payment is scheduled |
| Is there a £300 Universal Credit payment? | No nationwide £300 payment has been announced |
| When is the next payment date? | No date exists for a new payment |
| Will normal Universal Credit continue? | Yes, for eligible claimants |
| Can claimants receive other financial assistance? | Yes, subject to eligibility |
| Is the Crisis and Resilience Fund available? | Yes, through local authorities in England |
The official DWP Cost of Living Payment information confirms that the previous payments covered qualifying periods between 2022 and 2024.
It is important to distinguish a new national payment from other forms of financial support. An increase in monthly Universal Credit, a council crisis payment or assistance with energy bills does not represent the return of the previous DWP scheme.
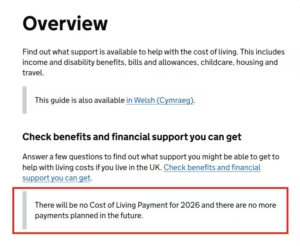
Official GOV.UK Cost of Living Payments page showing that DWP is not planning any further payments.
When Will the Next Universal Credit Cost of Living Payment Be Paid?
As of October 2026, the government has not announced another national Cost of Living Payment or a future payment window.
The previous payment schedule ended in February 2024.
Although government welfare policies can change following a Budget or other policy announcement, claimants should not assume that the former payment programme will restart.
This is particularly relevant when online posts refer to supposed £200, £300 or £500 DWP payments.
Some of these claims confuse historical payments with current benefits, council assistance or proposed support measures that have not become government policy.
From a household financial planning perspective, relying on an unconfirmed payment can create unnecessary financial risk.
For example, a household expecting an additional £300 to cover rent could experience arrears if the payment never arrives.
Until the government announces a new scheme, any financial plan should be based on confirmed benefit entitlements and income.
When Was the Last Universal Credit Cost of Living Payment Paid?
The last means-tested Cost of Living Payment was £299.
Most eligible Universal Credit claimants received it between 6 February and 22 February 2024.
This was the final instalment of the £900 means-tested Cost of Living Payment package covering 2023/24.
The three payments were:
- £301 between 25 April and 17 May 2023.
- £300 between 31 October and 19 November 2023.
- £299 between 6 February and 22 February 2024.
Together, these payments totalled £900 for households that qualified for all three.
Earlier, during 2022, eligible households could receive another £650 across two instalments.
Therefore, a household qualifying for every means-tested payment across both programmes could have received £1,550.
This was not a guaranteed total for every Universal Credit claimant. Each payment had its own qualifying conditions.
Complete Universal Credit Cost of Living Payment History
| Payment | Amount | Payment dates for most eligible UC claimants | Qualifying assessment-period end date |
| First 2022 payment | £326 | 14–31 July 2022 | 26 April–25 May 2022 |
| Second 2022 payment | £324 | 8–23 November 2022 | 26 August–25 September 2022 |
| First 2023 payment | £301 | 25 April–17 May 2023 | 26 January–25 February 2023 |
| Second 2023 payment | £300 | 31 October–19 November 2023 | 18 August–17 September 2023 |
| Final 2024 payment | £299 | 6–22 February 2024 | 13 November–12 December 2023 |
These dates relate specifically to qualifying Universal Credit claimants. Payment windows for people receiving tax credits only were sometimes different.
The distinction matters for anyone checking older bank statements or investigating a previously missing payment.
Who Was Eligible for the Previous Universal Credit Cost of Living Payments?
Eligibility depended on receiving a qualifying benefit during the relevant assessment period.
The previous means-tested programme included people receiving:
- Universal Credit.
- Pension Credit.
- Income-based Jobseeker’s Allowance.
- Income-related Employment and Support Allowance.
- Income Support.
- Child Tax Credit.
- Working Tax Credit.
For Universal Credit claimants, entitlement was linked to the date on which their monthly assessment period ended.
How Did the Qualifying Assessment Period Work?
Consider the final £299 payment.
A claimant generally needed to be entitled to a Universal Credit payment for an assessment period ending between 13 November and 12 December 2023.
For example, if someone’s assessment period ended on 10 December 2023 and they had a qualifying award, they could meet the relevant date condition.
However, someone whose assessment period ended on 15 December would not satisfy that particular qualifying window through Universal Credit.
This illustrates why receiving Universal Credit during a calendar month did not always guarantee eligibility for the corresponding Cost of Living Payment.
What If Someone Had a £0 Universal Credit Award?
A nil award could affect eligibility.
A Universal Credit payment may have been reduced to £0 because of earnings, increased household income, savings or a sanction.
Under the previous payment rules, claimants with a nil award for the relevant period were generally excluded.
However, some exceptions applied.
For example, a person whose benefit was reduced to £0 because of certain deductions, such as money being paid directly to a landlord, could still qualify. Some people receiving hardship payments could also remain eligible.
That is why a historical £0 bank payment is not always enough to determine entitlement without examining the claimant’s Universal Credit statement.
Did Couples Receive Two Cost of Living Payments?
No. Joint Universal Credit claims generally received one qualifying Cost of Living Payment for the household, not one payment for each partner.
A couple qualifying for the £299 instalment would therefore receive £299 between them rather than £598.
Equally, a claimant receiving more than one qualifying benefit could not necessarily receive duplicate payments from DWP and HMRC.
What Happens If a Previous Cost of Living Payment Was Never Received?
Although the national programme has ended, some historical entitlement questions can still arise.
DWP guidance explains that an eligible claimant may receive a payment later if their qualifying benefit is awarded retrospectively.
For example, somebody whose Universal Credit entitlement for a historical qualifying period is corrected may become eligible for a payment that was previously missing.
A retrospective payment is not a newly introduced 2026 Cost of Living Payment. It relates to entitlement under the previous programme.
How to Check a Missing Payment?
- Check bank statements covering the original payment window and any later period when a payment might have arrived.
- Look for historical references such as “DWP COL” or “HMRC COLS”.
- Review the Universal Credit statement for the relevant qualifying assessment period.
- Check whether earnings, sanctions or other adjustments resulted in a nil award.
- Contact the office responsible for the qualifying benefit if the payment appears to be missing.
- Ask for an explanation or reconsideration if the eligibility decision appears incorrect.
If the DWP has overlooked information affecting eligibility, a claimant can ask the department to reconsider the decision.
This is especially important where a previous benefit decision was later revised.
Are Universal Credit Payments Still Being Made in 2026?
Yes. Universal Credit itself continues to operate.
The end of the separate Cost of Living Payment programme does not affect a person’s entitlement to ordinary Universal Credit.
Universal Credit is generally paid monthly in England, Wales and Scotland, although people in Scotland can choose twice-monthly payments.
Payment amounts depend on individual circumstances, including household composition, earnings, children, housing costs and applicable benefit elements.
When Will Normal Universal Credit Be Paid?
A person’s regular payment date usually depends on their monthly assessment period.
After the first payment, Universal Credit is normally paid on the same calendar date each month.
For example, an assessment period ending on the 10th would usually result in payment on the 17th.
If the normal payment date falls on a weekend or bank holiday, payment is generally brought forward to the previous working day.
This is an adjustment to the existing benefit payment date, not additional financial assistance.
Our explanation of DWP bank holiday payment changes covers how early payments affect claimants and why they should not be mistaken for a government bonus.
People receiving their money earlier should remember that the following regular payment will usually remain on its normal schedule.
How Much Universal Credit Can You Receive in 2026/27?
One of the most important financial developments in 2026 is the increase in Universal Credit standard allowances.
The standard allowance rose by approximately 6.2% in April 2026.
However, the precise amount received depends on eligibility for additional elements and the deductions applying to each claim.
Universal Credit Standard Allowance Rates for 2026/27
| Household type | 2025/26 monthly rate | 2026/27 monthly rate |
| Single, under 25 | £316.98 | £338.58 |
| Single, 25 or over | £400.14 | £424.90 |
| Couple, both under 25 | £497.55 | £528.34 |
| Couple, one or both aged 25 or over | £628.10 | £666.97 |
These figures represent standard allowances, not guaranteed take-home payments.
A single claimant aged 25 or over, for instance, has a standard allowance of £424.90 in 2026/27, compared with £400.14 in 2025/26.
That is an increase of £24.76 per month, equivalent to approximately £297.12 annually if received at that rate for 12 months.
These changes are different from the old Cost of Living Payments because they form part of the regular benefit calculation rather than arriving as separate one-off payments.
Other changes introduced in April 2026 can also affect awards, including the removal of the two-child limit and different rates for the limited capability for work and work-related activity element.
A person’s total award may therefore rise by a different percentage from the standard allowance, or in some cases be affected adversely by changes to other elements.
How Does Employment Income Affect Universal Credit?
Universal Credit can also support people who are employed or self-employed.
Under the current earnings taper, Universal Credit is generally reduced by 55p for every additional £1 of relevant earnings once any applicable work allowance has been taken into account.
That represents a 55% withdrawal rate on those earnings.
For example, if a worker earns an additional £200 of net income above their applicable work allowance, their Universal Credit may fall by £110.
They would still be £90 better off overall in this simplified example, before considering any other changes in circumstances.
For households with irregular work patterns, overtime or variable earnings, understanding this relationship can be more useful than waiting for an unconfirmed one-off payment.
What Financial Support Has Replaced Cost of Living Payments in 2026?
The government has moved away from the previous programme of automatic national means-tested payments.
Instead, assistance is available through different systems, including local crisis support, ordinary benefits, housing assistance and energy-bill reductions.
The type and amount of support available are not the same for every household.
1. Crisis and Resilience Fund
The Crisis and Resilience Fund (CRF) is one of the most significant support arrangements introduced in England during 2026.
It operates from 1 April 2026 to 31 March 2029 and provides funding to local authorities to support low-income households experiencing financial difficulty.
Unlike the previous national Cost of Living Payments, the CRF is not a fixed amount automatically paid to everyone receiving Universal Credit.
Councils administer their own local arrangements within the government’s framework.
The fund supports people experiencing unexpected financial shocks and aims to prevent financial crises from becoming more serious.
Potential reasons for seeking assistance may include:
- An unexpected essential household expense.
- A sudden reduction in income.
- Difficulty obtaining food or basic household necessities.
- Emergency heating or energy costs.
- Essential domestic appliances breaking down.
- Short-term housing financial difficulties.
Local crisis payments are intended to prioritise financial need.
As a result, two people receiving similar Universal Credit awards may receive different assistance depending on their circumstances and local authority.
How Much Can Someone Receive From the Crisis and Resilience Fund?
There is no single nationally guaranteed CRF payment amount for every eligible household.
Councils determine assistance according to their schemes, financial resources and the applicant’s circumstances.
Support can include cash payments or other methods of assisting households, depending on the local arrangements.
Our assessment of the framework indicates that applicants should focus on clearly explaining their immediate financial difficulty rather than expecting a standard payment simply because they receive Universal Credit.
How to Apply for Crisis and Resilience Fund Support?
- Identify the local authority responsible for your area.
- Visit its website and search for Crisis and Resilience Fund or Crisis Payment.
- Check the council’s eligibility conditions.
- Explain the financial difficulty or emergency.
- Provide requested financial or household information.
- Submit the application using the council’s approved process.
The official Crisis and Resilience Fund guidance explains the national framework and directs residents towards their local council.
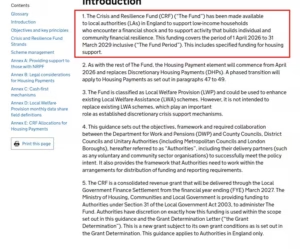
Official DWP Crisis and Resilience Fund guidance showing the funding period from 1 April 2026 to 31 March 2029 and the role of local authorities
2. Help With Rent and Housing Costs
Housing costs can represent one of the largest financial pressures for Universal Credit households.
Some claimants receive a housing costs element within their Universal Credit award, depending on their circumstances.
For private tenants, the eligible amount is often affected by Local Housing Allowance rates, household size and local rental market rules.
Our analysis of how much Universal Credit pays towards private rent explains why the housing element may not cover the entire rental amount.
In England, the Crisis and Resilience Fund also includes housing-related assistance, with arrangements introduced in place of the previous Discretionary Housing Payment framework.
This support is separate from the normal Universal Credit housing element.
Someone struggling with a shortfall between their rent and benefits should therefore examine both their existing UC entitlement and any suitable council assistance.
3. Energy Bill Support and the £150 Warm Home Discount
Energy support remains available in 2026, although it operates differently from the previous national Cost of Living Payments.
The government introduced measures intended to reduce average energy costs, including an average £150 reduction in household energy costs from April 2026.
There is also the separate Warm Home Discount.
For winter 2026/27, qualifying households can receive a £150 discount on their electricity bill through the scheme.
This is not the same as receiving £150 in cash from DWP.
The discount is generally applied through the energy supplier, and qualifying conditions depend on the nation and scheme arrangements.
For Universal Credit households, it is worth checking whether the account holder or their partner satisfies the relevant eligibility requirements.
Other potential assistance includes Cold Weather Payments, where the appropriate benefit and weather conditions are met.
Claimants should avoid assuming that every energy-related payment advertised online is a new Universal Credit grant.
4. Council Tax Reduction and Household Discounts
Council Tax Reduction can provide additional financial relief to some low-income households.
Eligibility depends on the local scheme and the household’s circumstances.
Receiving Universal Credit does not automatically establish the amount of Council Tax Reduction available.
Other reductions may apply to particular household situations, including some disability-related circumstances.
For households where disability affects the property or the occupants’ needs, our breakdown of disabilities that qualify for Council Tax Reduction explains the different categories of relief.
Checking all applicable reductions can help reduce ongoing bills rather than relying entirely on occasional financial assistance.
What Cost of Living Support Is Available in Scotland, Wales and Northern Ireland?
The Crisis and Resilience Fund described above applies to England.
Residents in other UK nations should use their own government’s assistance arrangements.
| Nation | Potential support route | Important distinction |
| England | Crisis and Resilience Fund | Administered through local councils |
| Scotland | Scottish Welfare Fund | Crisis Grants and Community Care Grants may be available |
| Wales | Discretionary Assistance Fund | Emergency Assistance Payments may support essential needs |
| Northern Ireland | Discretionary Support | Support depends on financial circumstances and scheme conditions |
The relevant schemes have different eligibility rules and application processes.
A person receiving Universal Credit in Glasgow, Cardiff or Belfast should therefore avoid relying on eligibility information written specifically for an English local authority.
Can Universal Credit Claimants Receive an Advance Instead?
People who need money urgently may be able to request a Universal Credit advance, depending on their circumstances.
However, an advance is not the same as a free Cost of Living Payment.
Most Universal Credit advances have to be repaid through deductions from future benefit payments.
For example, a claimant awaiting their first Universal Credit payment may be able to request an advance based on their expected entitlement.
Although this could help with an immediate financial problem, the resulting repayments may reduce the money available in later months.
The distinction is particularly important because misleading online claims sometimes describe substantial advances as free money.
The widely discussed Universal Credit £1,500 loophole is not an official scheme guaranteeing claimants an extra £1,500.
From a financial planning perspective, people should distinguish between:
- Non-repayable support, such as an eligible local crisis grant.
- A legitimate benefit award already owed to them.
- A repayable Universal Credit advance.
- A loan or other form of borrowing.
These forms of support have very different implications for future disposable income.
How Should Universal Credit Households Manage Living Costs Without Another Payment?
The absence of a national one-off payment makes regular income and expenditure management more important.
Our financial analysis identifies several practical areas households can review.
Review the Full Universal Credit Statement
A Universal Credit award may include different elements relating to children, housing, caring responsibilities or health conditions.
Changes in these circumstances can affect entitlement.
Claimants should check that relevant information is accurate and report changes promptly.
Prioritise Essential Household Payments
Rent, energy, food and essential travel generally require particular attention when planning a monthly budget.
A benefit payment that arrives early because of a bank holiday should not be treated as extra income.
Check Local Financial Assistance Before Borrowing
A person experiencing an unexpected bill should investigate local council assistance before committing to expensive borrowing.
The Crisis and Resilience Fund may offer support in appropriate circumstances, although payments are not guaranteed.
Examine Housing Costs and Available Reductions
Households paying a substantial proportion of their income towards rent or Council Tax may benefit from checking their benefit entitlement and local reductions.
Where financial pressure is persistent, reviewing recurring expenditure can produce a longer-term improvement than relying on a single emergency payment.
Understand the Effect of Variable Earnings
Employed claimants should monitor how overtime, bonuses and irregular pay affect their Universal Credit assessments.
Because of the 55% taper, an increase in earnings may not translate into an equivalent increase in total disposable income, although working additional hours can still leave the claimant financially better off.
These checks are particularly relevant for part-time workers, self-employed people and households with fluctuating monthly earnings.
Are Claims About New £200, £300 or £500 DWP Payments Genuine?
Not every online claim about a government payment is accurate.
Some headlines refer to historical Cost of Living Payments, while others refer to local council assistance or separate benefit programmes.
For instance, the £300 amount frequently appearing in social media posts may relate to the payment originally made during October and November 2023.
A £200 payment may instead refer to a pensioner benefit, a locally administered scheme or another form of assistance.
Eligible pensioners can receive Winter Fuel Payments under the rules for winter 2026/27. These payments are separate from Universal Credit and have their own qualifying conditions.
Our explanation of DWP £200 pensioner eligibility distinguishes the winter heating scheme from general cost-of-living assistance.
Similarly, an early monthly Universal Credit payment caused by a bank holiday should not be interpreted as a new DWP bonus.
The central test is whether the payment has been officially announced, whether clear eligibility criteria exist and whether the correct government department administers it.
How to Avoid Universal Credit Cost of Living Payment Scams?
Misleading payment claims can also expose people to financial fraud.
Scammers may send texts, emails or social media messages suggesting that claimants are entitled to a newly announced payment.
These messages might direct people to websites requesting:
- Bank account information.
- National Insurance numbers.
- Universal Credit login details.
- Passwords or security codes.
- An upfront fee to release the payment.
The previous national Cost of Living Payments were generally issued automatically to eligible claimants.
Someone claiming that a new payment can only be accessed by clicking an unfamiliar link should therefore be treated with caution.
The safest approach is to access government services independently through the official website rather than through an unsolicited message.
What Should You Do If You Need Financial Help Right Now?
If you currently receive Universal Credit and are struggling with essential expenses, you do not need to wait for a new national Cost of Living Payment that has not been announced.
A practical approach is to review your existing UC entitlement, identify your most urgent financial needs, and contact the relevant support service.
For example:
- Someone unable to afford food or heating may need to investigate local emergency assistance.
- A private tenant facing a rental shortfall may need housing-related support.
- A low-income household struggling with Council Tax should examine available reductions.
- A person experiencing an unexpected reduction in earnings should check whether their Universal Credit award has been recalculated correctly.
The appropriate response depends on the circumstances.
Financial support is most effective when the claimant understands whether it is automatic, discretionary, repayable or dependent on a separate application.
Final Thoughts: When Will the Universal Credit Cost of Living Payment Be Paid?
For anyone asking “Universal Credit cost of living payment when will it be paid?”, the position in October 2026 is clear.
There is no new nationwide payment scheduled for 2026, and the government has no further Cost of Living Payments currently planned.
The final means-tested payment was £299, made to most qualifying Universal Credit claimants between 6 February and 22 February 2024.
Nevertheless, normal Universal Credit payments continue, standard allowances increased in April 2026, and qualifying households may receive other assistance.
In England, the Crisis and Resilience Fund provides an important route to support for households facing financial shocks. Other help may be available through energy schemes, housing assistance and local Council Tax arrangements.
Rather than budgeting for an unconfirmed government payment, claimants should check the support available under the current rules and make sure their existing benefit entitlements are accurate.
Frequently Asked Questions
Will Universal Credit claimants receive another Cost of Living Payment in 2026?
No. The government has confirmed that no national Cost of Living Payment will be made in 2026, and there are no further payments currently planned.
When was the last £299 Cost of Living Payment made?
Most eligible Universal Credit claimants received the final £299 payment between 6 February and 22 February 2024.
Is DWP paying £300 to Universal Credit claimants in October 2026?
No new nationwide £300 Cost of Living Payment has been announced for October 2026. The previous £300 instalment was paid to most eligible UC claimants in October and November 2023.
Will Universal Credit payments increase in 2026?
Yes. The Universal Credit standard allowance increased by approximately 6.2% in April 2026. The actual amount someone receives depends on their circumstances, additional elements and deductions.
What replaced the Household Support Fund in 2026?
In England, the Crisis and Resilience Fund began on 1 April 2026 and is scheduled to run until 31 March 2029. It provides funding for local crisis assistance and financial resilience programmes.
Can someone receiving Universal Credit get money from their local council?
Potentially, yes. Local authority support may be available to low-income households experiencing financial difficulty, but eligibility and payment amounts depend on the individual scheme.
Can I still receive an old Cost of Living Payment if DWP made a mistake?
Possibly. If a historical qualifying benefit decision is revised and you become entitled to an earlier payment, DWP may still owe it. Contact the office responsible for your qualifying benefit.
Do couples on Universal Credit receive separate Cost of Living Payments?
Under the previous national scheme, a qualifying joint claim received one payment per household rather than separate amounts for each partner.
Is the £150 Warm Home Discount a Universal Credit payment?
No. The Warm Home Discount is an energy-bill discount for qualifying households. It is not a new national Universal Credit Cost of Living Payment.
How can I check my next Universal Credit payment date?
Sign in to your Universal Credit account and review your payment statement. Your normal payment date generally remains the same each month, except where weekends, bank holidays or individual circumstances affect it.